
New vs Established: Which Home Delivers Better Long-Term Value?
Choosing where and how to buy is one of the biggest financial decisions you will make, whether you are looking for somewhere to live or an asset to hold. For many buyers, the question comes down to whether it is better to purchase an established home or build new in a growing community. There is no one-size-fits-all answer, but understanding the long-term costs, lifestyle benefits and future opportunities attached to each option can help you make a more informed decision.
While many considerations are shared, the way you assess them may differ depending on your goals. Here, we highlight key points for both home buyers and investors to help you compare the options from the perspective most relevant to you.
Understanding the difference
An established home is a previously owned and occupied property, typically located in a suburb with existing infrastructure and amenities.
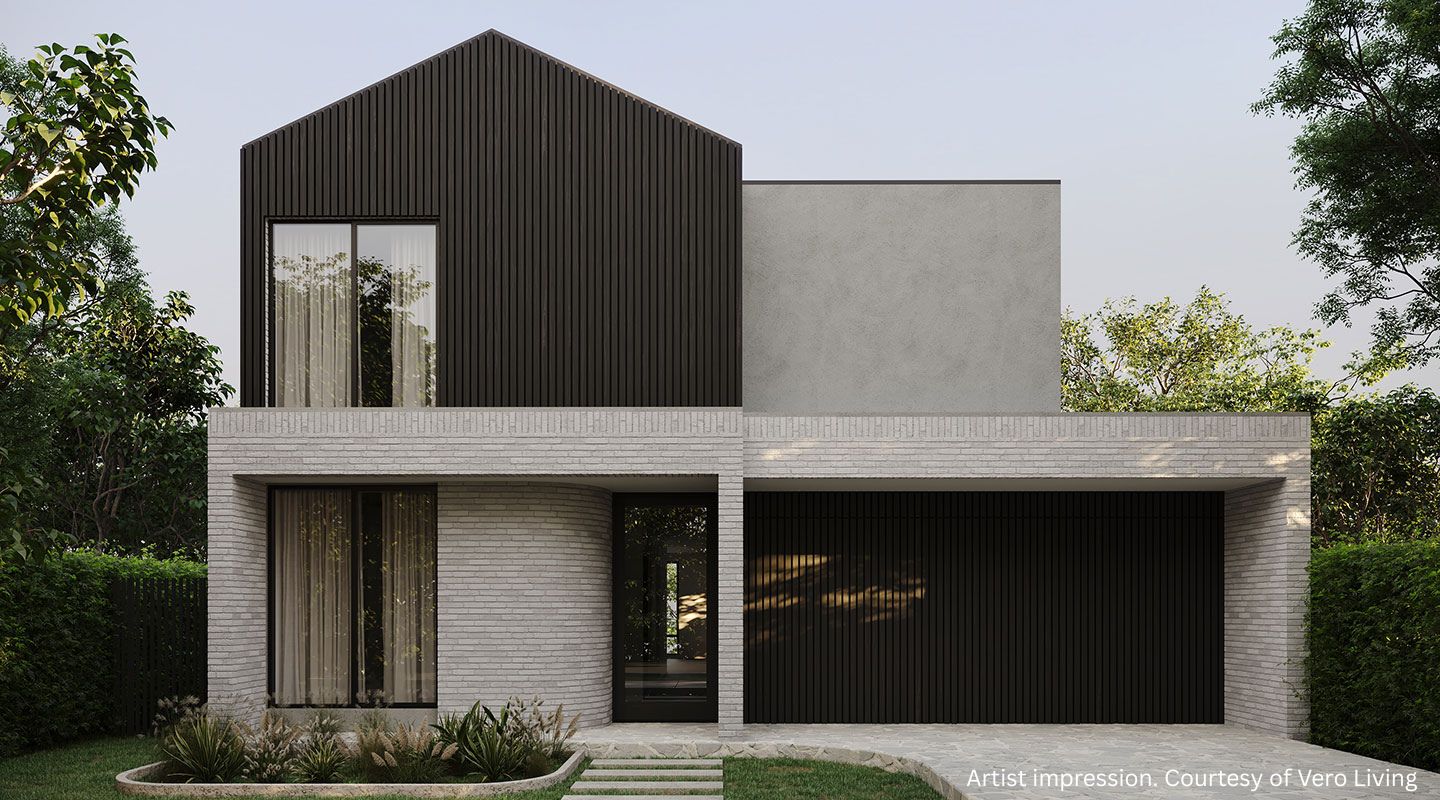
A new home generally refers to a recently built property or a house and land package within a new or emerging community. These homes are built to current construction and energy-efficiency standards and may form part of a masterplanned neighbourhood designed for future growth and liveability.
Both options have advantages, but for many buyers, the benefits of a brand-new home, including modern design, energy efficiency and lower maintenance requirements, are increasingly influencing the decision.
For home buyers: Building new gives you greater freedom to choose a design, finishes and features that suit your lifestyle now and into the future.
For investors: Established homes may offer access to well-established suburbs, while new homes can provide modern tenant appeal, lower maintenance requirements and fewer immediate upgrade costs.
Upfront costs versus long-term expenses
An established home can sometimes appear more affordable upfront, particularly in an older suburb. However, the purchase price is only one part of the comparison. Maintenance, renovations, ageing appliances and energy use can add significantly to the cost of ownership.
New homes are designed for modern living and typically require less maintenance in the early years. Buyers may also be able to select a floorplan, finishes and features from the outset, creating a home personalised to their lifestyle and reducing the need for major changes after moving in.
A house and land purchase has its own considerations, including build time, progress payments and the potential need for temporary accommodation. When comparing value, consider both what you will pay today and the likely costs over the years ahead.
For home buyers: Look beyond the purchase price. Renovations, maintenance and energy costs can add up, while a new home may offer greater early cost certainty.
For investors: Consider the total holding cost, including maintenance, finance, vacancies and the timing of rental income.
Maintenance and peace of mind
One of the most overlooked costs of property ownership is maintenance. Older homes often come with character and established surroundings, but they can also bring unexpected expenses. Roofing, plumbing, electrical systems and appliances may require repairs or replacement as they age, creating costs that are difficult to predict.
In contrast, the major components of a new home are typically brand new and may be supported by builder and product warranties in the early years. This can provide greater certainty around maintenance costs and reduce the likelihood of significant unexpected expenses shortly after moving in.
Whether you’re purchasing a home to live in or an investment property, greater certainty around maintenance can make budgeting easier and help reduce financial surprises.
Lifestyle, convenience and location
Established suburbs often offer schools, shops, transport and services that are already operating. Buyers can visit the area, assess its amenity and understand how it functions before purchasing.
Today’s masterplanned communities are designed to deliver much more than housing, combining homes with newly planned parks, walking and cycling paths, schools, childcare, recreation facilities and local services as communities grow. Designed around contemporary lifestyle needs, these neighbourhoods support greater convenience, connectivity and active living.
For many buyers, a growing community offers the opportunity to be part of a neighbourhood that will continue to develop and flourish around them.
For home buyers: Consider how the location supports your lifestyle today, as well as what is planned for the future.
For investors: Consider both the amenity already available and confirmed future delivery. New infrastructure and contemporary community design may support ongoing tenant demand and contribute to the area’s long-term appeal.
Community and connection
A home is about more than the dwelling itself. Access to open space, local facilities and opportunities to connect with neighbours can shape the experience of living in a place.
Masterplanned communities are often designed around parks, trails, recreation and shared spaces that support active lifestyles and local connection. Many are planned with the goal of creating a 20-minute neighbourhood, where everyday essentials such as schools, childcare, parks, local services and open spaces are located closer to home. As communities grow, residents can enjoy both convenience and a strong sense of place, while building new connections within their neighbourhood.
Established suburbs may already have strong community networks and recognised local destinations, although the experience varies between locations.
Beyond lifestyle benefits, attractive and well-connected neighbourhoods can also contribute to the long-term appeal of a property for future buyers and tenants.
Rental demand and tenant appeal
Established homes can benefit from demonstrated tenant demand in mature locations, although older layouts, condition and energy performance may affect how they compare with newer listings.
New homes can stand out to tenants through their presentation, practical layouts, energy efficiency and lower maintenance needs. Investors should still consider local supply, including whether several similar properties may become available at the same time.
Regardless of property type, investors should research vacancy rates, comparable rents, employment access, local supply and the future delivery of housing and infrastructure.
For home buyers: Features that appeal to tenants may also support future resale appeal if your circumstances change.
For investors: Look beyond advertised rent and assess the depth of local demand, competing supply and the likely tenant profile.
Tax, depreciation and holding costs
New and established investment properties can have different tax, depreciation and cash flow outcomes. New homes may offer depreciation benefits, lower maintenance costs and fewer immediate upgrade expenses, while established properties may require earlier spending on repairs or upgrades.
Rates, insurance, finance and property management costs can apply to either option. A house and land purchase may also involve a construction period before rental income begins. As tax rules and individual circumstances vary, buyers should obtain qualified financial and taxation advice before making a decision.
For home buyers: Tax depreciation is generally an investor consideration, but energy, maintenance and running costs still affect long-term affordability.
For investors: Assess the full cost and timing of ownership rather than relying on the purchase price or a potential tax benefit alone.
Government support and buyer incentives
For some buyers, purchasing or building a new home may provide access to grants, concessions or government-supported home ownership schemes that help reduce upfront costs. Some forms of support may also apply to eligible established home purchases, making it important to understand what assistance may be available before making a decision.
As eligibility criteria, property value thresholds and program settings can change over time, buyers should confirm current requirements through official government sources and seek independent advice where appropriate.
Read our guide to government support, grants and buyer incentives.
Future growth potential
Property performance is influenced by factors including supply and demand, infrastructure investment, employment, population growth and the quality of the individual property. No future outcome can be guaranteed.
Established suburbs provide a history that buyers can research, although existing demand and amenity may already be reflected in the purchase price.
Growth areas offer the opportunity to buy into a community as it develops. New infrastructure, schools, retail, transport and community facilities can improve liveability and strengthen the area’s appeal over time. Buyers should still research confirmed infrastructure, delivery timeframes and local housing supply.
For home buyers: Prioritise whether the area will continue to suit your household, not growth expectations alone.
For investors: Compare proven demand with future potential, and test assumptions against local data and confirmed infrastructure commitments.
Where to next
While the right choice depends on your goals, building new can offer greater design choice, modern efficiency, lower early maintenance requirements and the opportunity to join a community planned for the future.
A sound decision looks beyond the initial price to what the property may cost, earn and deliver throughout the time you own it.
If you are buying a home to live in, explore our communities to see how masterplanned neighbourhoods are being brought to life across Melbourne’s growth corridors, what has already been delivered and what’s planned next.
If you are considering a property investment, explore our latest articles and guides for insights into growth areas, long-term ownership considerations and today’s property market.This article provides general information only and does not take into account your personal circumstances, financial situation or objectives. It is not financial, taxation or legal advice. You should seek independent professional advice before making a property decision.